rb-insider-logo
Insights
3 min read
Share this article:
News
10 min read

Today, Chinese brands account for around 26% of all new vehicle sales, yet they represent just 3.8% of used vehicle transactions. The reason is simple: the used market still largely reflects purchasing decisions made three to seven years ago, when Chinese manufacturers had a much smaller presence, meaning the real test for the industry hasn’t arrived yet.

As hundreds of thousands of vehicles move through their first ownership cycle and enter the used market, buyers won’t simply be assessing price, technology or driving range. They’ll be evaluating something potentially more important: long-term support.

Retained values are ultimately a measure of confidence, not just in the vehicle itself, but in the ecosystem around it. Buyers need to know that it can be serviced, repaired, insured and supported throughout its life.

RedBook analysis indicates the Chinese-brand vehicle parc could approach 1.28 million vehicles by 2027, with approximately 950,000 vehicles expected to be on Australian roads by 2026. At the same time, Chinese brands have become a dominant force in the EV market, accounting for 62.5% of EV sales year-to-date, up sharply from just 18% two years ago.

The question is no longer whether these vehicles will be sold. The question is whether the support ecosystem can scale at the same pace.

RedBook Insider - Mechanic

While Chinese brands collectively operate more than 550 sales and service locations nationally, vehicle volumes are growing even faster. RedBook analysis shows some emerging brands are now placing significantly higher vehicle loads on each support location than established manufacturers, raising questions about whether service, parts and repair infrastructure can scale at the same pace as the vehicle parc.

BYD provides an interesting illustration. The brand currently operates around 156 service centres, compared with Toyota’s 321 locations. On a sales-per-site basis, that equates to approximately 121 monthly sales per BYD location versus around 60 per Toyota location, effectively placing almost twice the vehicle load on each support site.

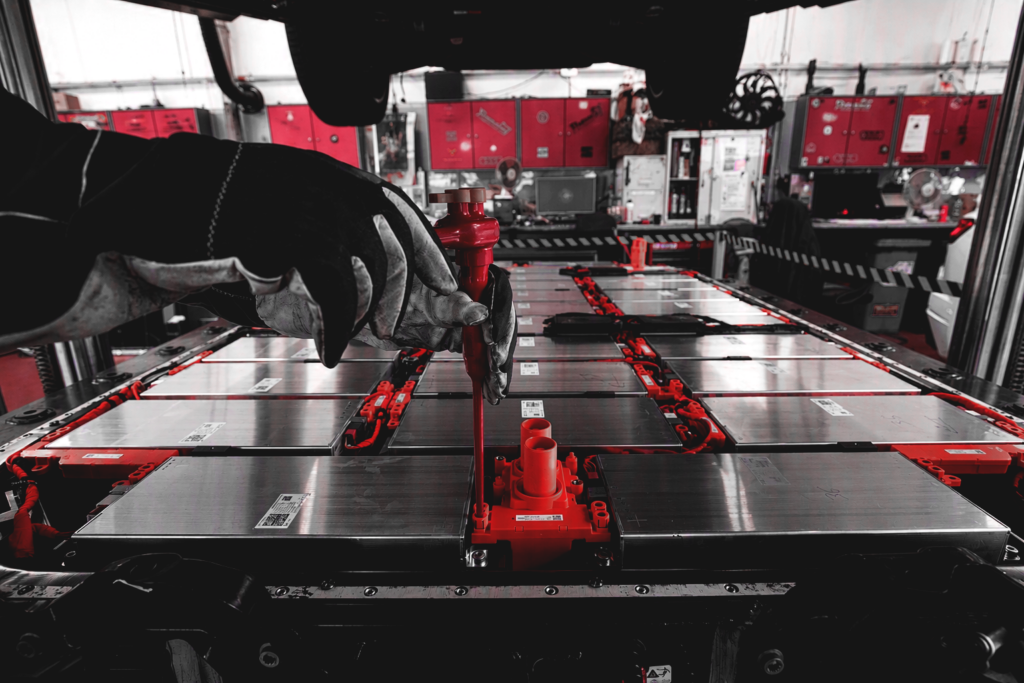
Importantly, this is not simply a servicing discussion. Modern EVs typically require 30-40% less routine maintenance than traditional internal combustion vehicles. The challenge lies elsewhere, including high-voltage diagnostics, specialist technician availability, replacement parts, collision repair capability and crash parts supply. This is where the retained value conversation intersects with the broader insurance ecosystem.

Parts availability and repair turnaround times directly influence insurer costs, customer satisfaction and total cost of ownership. If repair pathways become constrained or replacement components become difficult to source, those pressures can flow through insurance premiums, accident repair cycles and, ultimately, buyer confidence in the used market.

History shows that Japanese and Korean manufacturers faced similar challenges as they expanded their presence in Australia. The difference today is speed. Network development that once occurred over decades is now expected to keep pace with explosive growth in sales and vehicle parc.

With Chinese brands representing 26% of new vehicle sales but only just shy of 4% of used transactions, the largest wave of vehicles has yet to move through the ownership cycle. When it does, the market will begin answering an increasingly important question: can support infrastructure grow as quickly as the vehicles it is designed to support?

Because in the long run, retained values are not determined solely by what happens in the showroom. They are shaped by the confidence owners have that their vehicle can be maintained, repaired and supported for years to come.

Share this article:

LinkedIn logo

carsales for Business

Disclaimer:
The information presented in this article is true and correct at the time of publishing. business.carsales.com.au does not warrant or represent that the information is free from errors or omissions. The content is provided for informational purposes only and should not be construed as professional advice. For more details on our editorial standards and ethical guidelines, please visit our Editorial Guide Lines.